Single Close Construction Loans in Asheville NC: Build Your Dream Home in the Blue Ridge Mountains
Asheville, North Carolina, has long captivated those who seek both natural beauty and vibrant culture. Nestled in the Blue Ridge Mountains, this jewel of Western NC traces its roots back to the late 1700s when pioneer settlers carved homesteads from the mountain wilderness. Today, Asheville and its surrounding communities Weaverville, Black Mountain, Fairview, Swannanoa, and Arden continue to draw people eager to plant roots in one of the most breathtaking landscapes the Southeast has to offer. If you've dreamed of building a new home in this remarkable region, a single close construction loan in Asheville NC may be the smartest financing option available to you.
What Is a Single Close Construction Loan?
A construction to permanent loan commonly called a single close construction loan or one-time close loan combines your construction loan and your permanent loan into a single mortgage product with one closing. Rather than taking out a short-term construction loan and then refinancing into a traditional mortgage once your home is complete, you handle everything in a single transaction.
This is a significant and important benefit. With a traditional two-close process, borrowers face two separate applications, two appraisals, two sets of closing costs, and two closings. With a single close program, you go through loan closing just once dramatically reducing fees, paperwork, and stress throughout your construction project.
How the Loan Works: From groundbreaking to Move-In
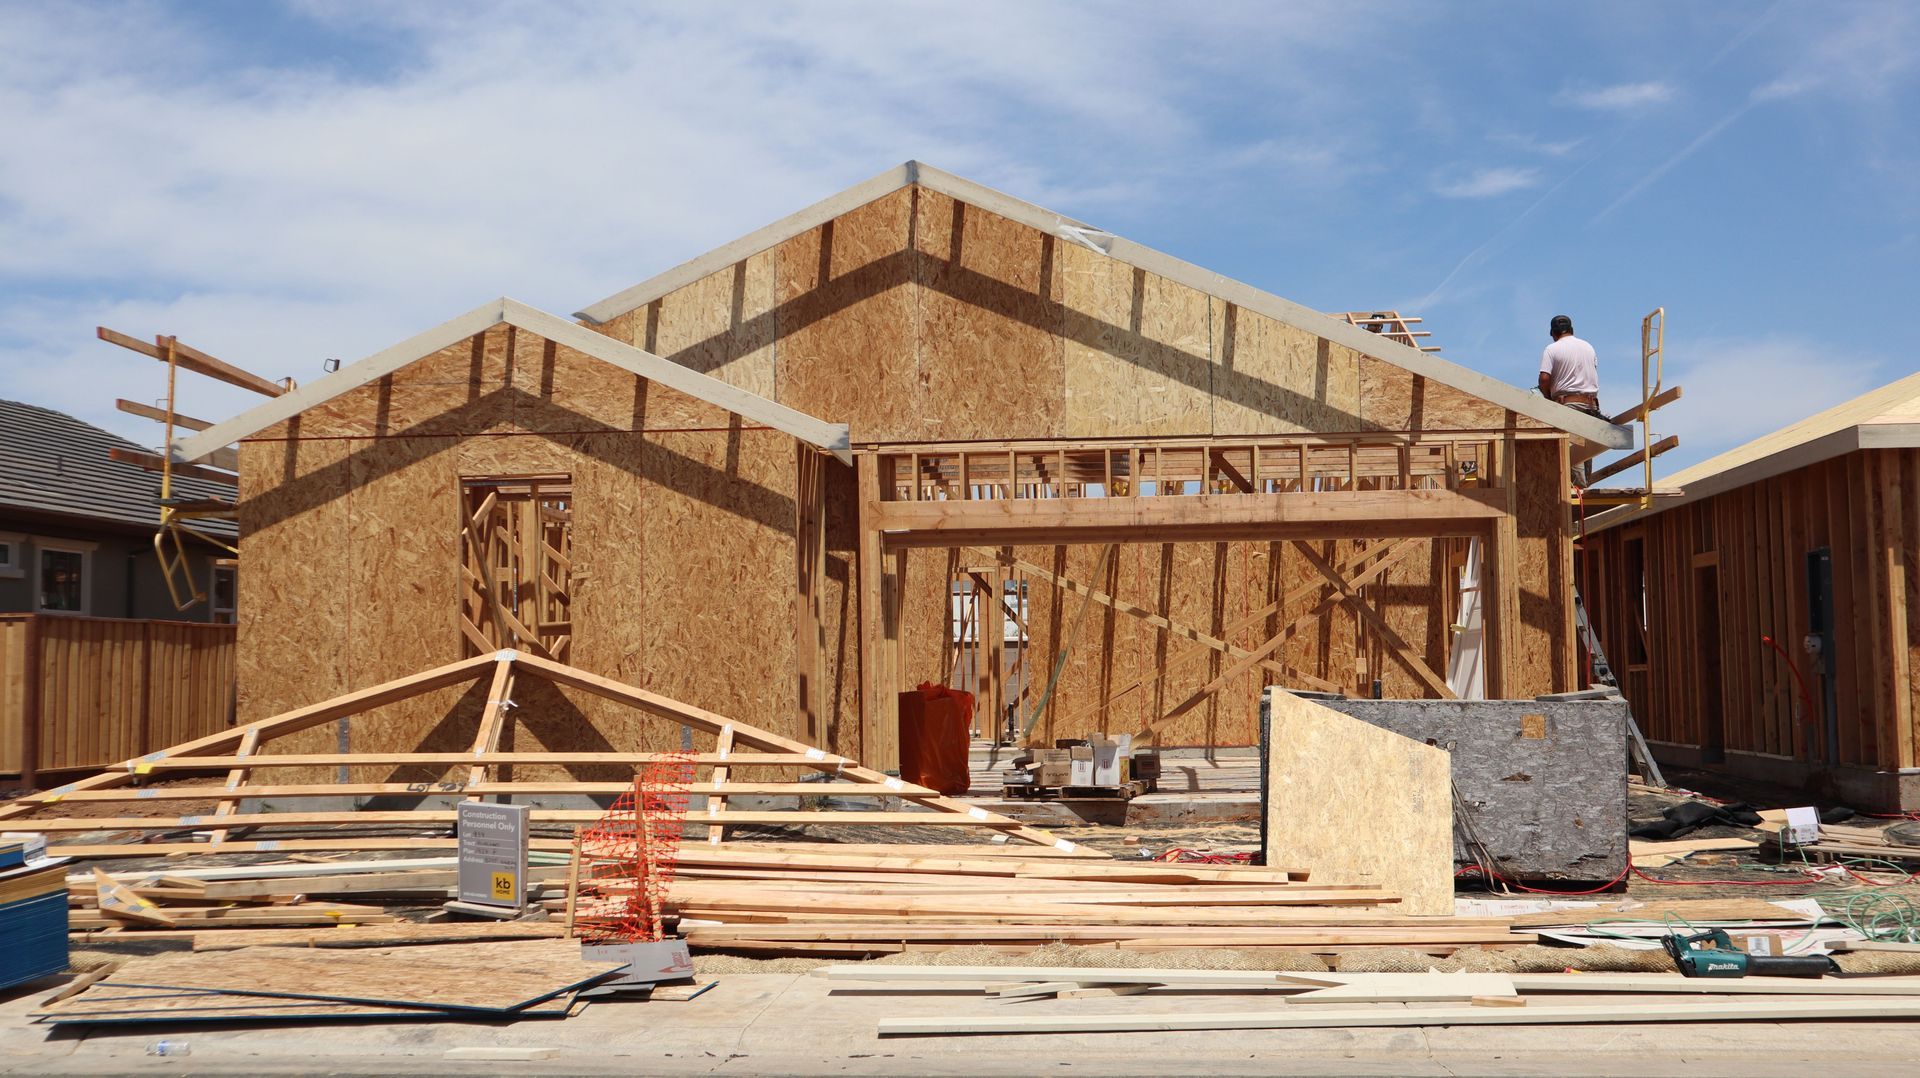
Once your loan approval is in place and construction begins, funds are distributed to your contractor and builders through a series of draw requests tied to completed project milestones. Your lender will order inspections at key stages foundation, framing, rough ins, and so forth before releasing each draw. This protects both the borrower and the lender by ensuring the project budget is being used appropriately and that work is progressing on schedule.
During the construction phase, most borrowers make interest only payments on the funds that have been drawn. This helps manage cash flow while your home is being built, since you're not yet paying principal on the full loan amount. Once construction reaches completion, the loan automatically converts to your permanent mortgage with a fixed rate and fully amortizing payments no need to reapply or go back to the bank.
Your interest rate is typically locked at the time of the original closing, shielding you from market fluctuations that might otherwise affect your financing during a lengthy build.
Down Payment, Equity, and Qualifying
To qualify for a single close construction loan in Asheville NC, lenders evaluate your credit score, income, existing debt, and the appraised future value of the property. Most programs require a minimum down payment — often as low as 3.5% for FHA one-time close loans or 0% for VA or USDA programs in rural areas surrounding Asheville.
If you already own the land, the equity you hold there can frequently be applied toward your down payment, reducing the out-of-pocket money you need to bring to closing. An appraisal is completed based on the approved plans and specifications for the home — a process sometimes called an "as completed" appraisal — to determine the loan amount you're eligible to borrow.
Project costs must be carefully documented. Your lender will review a detailed line item budget covering materials, permits, labor, and contingency reserves. Having a solid plan and a qualified licensed contractor in place before you submit your application is essential to keeping the process on track.
Why Asheville and Surrounding Communities Are Ideal for New Construction
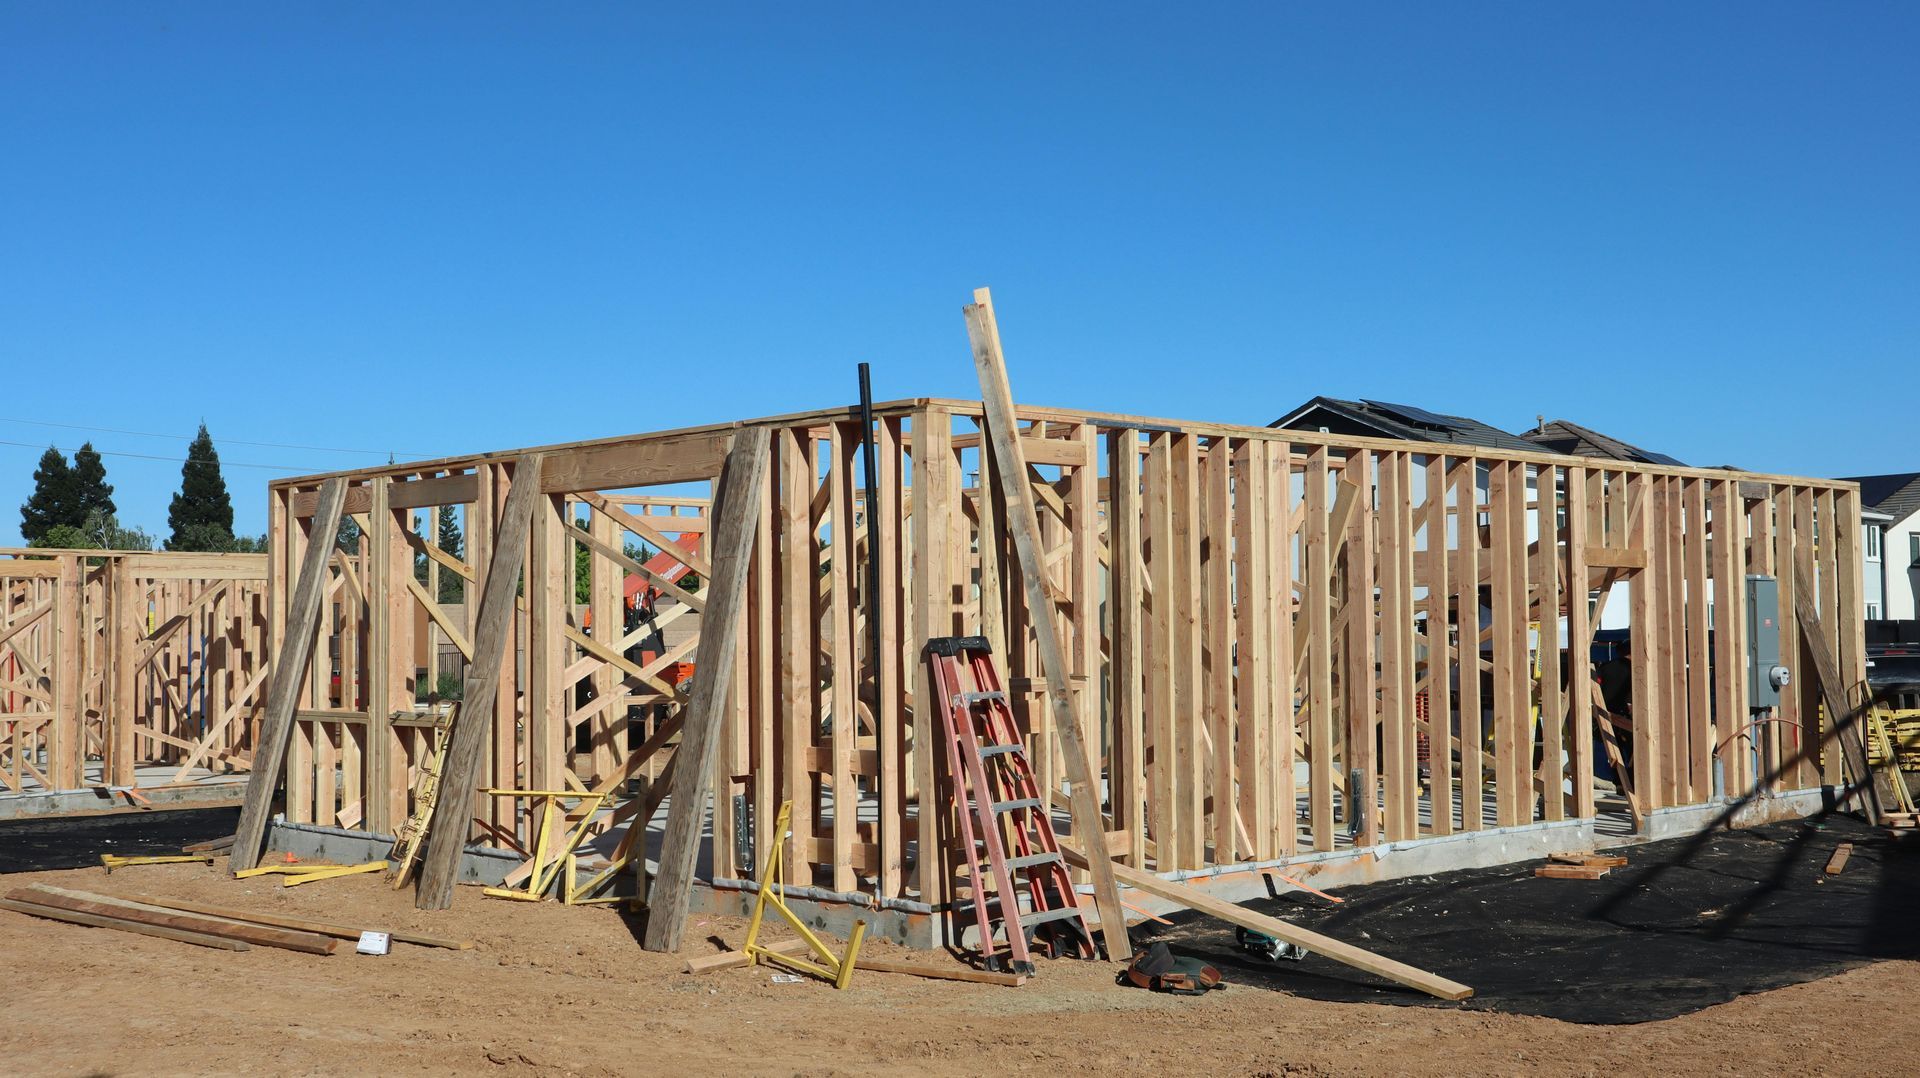
Asheville's market has experienced significant demand for housing, driven by its reputation as a top destination for retirees, remote workers, and outdoor enthusiasts. The city's rich architectural heritage from its iconic Art Deco downtown to historic Biltmore Village reflects a deep appreciation for well-crafted buildings. Whether you're envisioning a mountain modern retreat in Fairview, a craftsman-style cottage in Weaverville, or an energy-efficient new home on acreage in Madison County, new construction gives you the ability to build exactly what you envision.
Most lenders don't specialize in construction financing, which is why working with a local mortgage professional who understands the Western NC market, local builders, and regional permits requirements is so valuable. Bob Fabian brings that local expertise directly to your construction financing experience.
Key Benefits at a Glance
- One closing means one set of fees and a streamlined process
- Lock your interest rate before construction begins — protecting your future payment
- Interest only payments during the construction phase preserve cash flow
- Land equity may count toward your down payment
- Available for rural areas via USDA guaranteed programs
- Applies to renovation and purchase scenarios as well as raw land builds
- Transparent draw and inspections process keeps your project on budget
Start Building in the Blue Ridge
From the moment you search for the right property to the day you turn the key in your dream home, the single close construction loan is designed to make the path from foundation to finished house as smooth as possible. You'll have one loan, one lender, and a clear form of financing that carries you from the first shovel of dirt to your first night home.
Ready to explore your financing options? Contact Bob Fabian today to discuss how a single close construction loan in Asheville NC can turn your vision of mountain living into a place you truly own home to.