Single Close Construction Loans in Wake Forest, NC: One Loan, One Closing, One Dream Home
Wake Forest, NC has quietly become one of the most sought-after places to build a new home in the Triangle. With its small-town charm, top-rated Wake County schools, and easy access to Raleigh and Research Triangle Park, more families and retirees are choosing new construction over an existing home. If you've already started looking at land near Falls Lake, Heritage, or off Capital Boulevard, the next question is usually the same: how do I handle the financing without juggling two separate loans?
For most Wake Forest borrowers, the answer is a single close construction loan — also called a one time close, construction to permanent loan, or C2P loan. With one application, one underwriting process, and one closing, you can fund the land purchase, the construction phase, and your permanent mortgage in a single streamlined process.
What Is a Single Close Construction Loan?
A single close construction loan rolls two stages — the construction loan and the permanent mortgage — into one product. During the construction phase, your lender funds the builder through a structured draw schedule as work is complete and inspections pass. Once the certificate of occupancy is issued, the loan converts automatically into a long-term, 15-, 20-, or 30-year permanent loan at the interest rate you locked at closing.
Compare that to a traditional two-time close structure, where you'd need to qualify twice, pay two sets of costs, and gamble on where the permanent mortgage rate sits when construction wraps up. With a one time close construction loan in Wake Forest, NC, you avoid a second closing, you save time, and the financing is covered from groundbreaking to move in day.
Single Close vs. Two-Time Close at a Glance
- Closings: One vs. two
- Closing costs: One set vs. two sets
- Rate lock: Locked once vs. re-locked at conversion
- Underwriting: One round vs. requalifying mid-build
- Risk exposure: Lower vs. higher
Why Build a New Home in Wake Forest, NC?
Wake Forest sits at the northern edge of Wake County, just 17 miles north of downtown Raleigh and within an easy commute of RTP, North Hills, and Brier Creek. The town has grown roughly 75% since 2010, but unlike many Triangle markets, it still has buildable land, established custom builders, and large parcels in nearby Rolesville and Youngsville.
Buyers interested in building here are typically drawn to:
- The Wake Forest-Rolesville school district and its highly-rated K–12 options
- Walkable downtown Wake Forest and the historic district along South Main Street
- Outdoor amenities like Joyner Park, Smith Creek Soccer Center, and Falls Lake State Recreation Area
- Quick access to US-1 / Capital Boulevard and I-540 for commuters
- A lower cost-per-square-foot to build than comparable lots in Cary or North Raleigh
- A single close construction loan gives you the financing options to take advantage of those opportunities without competing in bidding wars for limited resale property.
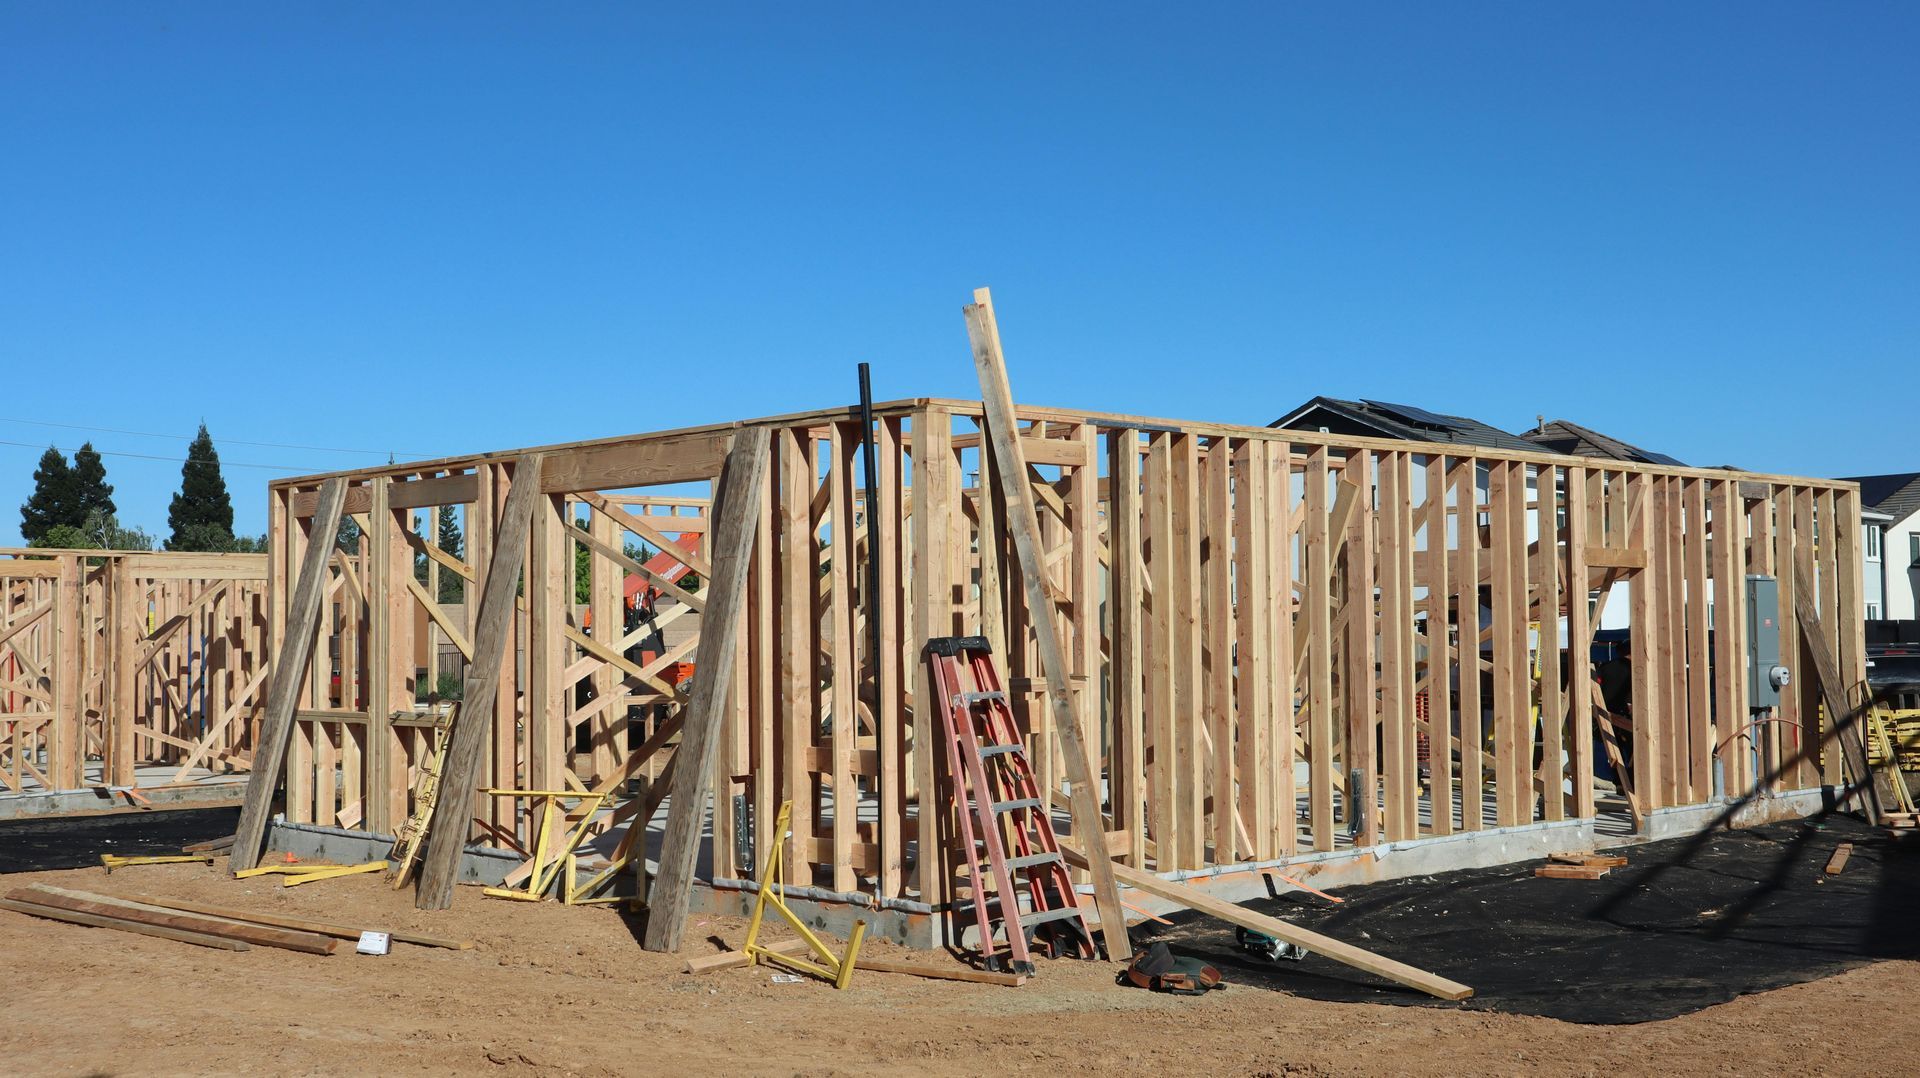
How a Single Close Construction Loan Works in Wake Forest
The process is more straightforward than most buyers expect. Here's the typical path when you work with Bob Fabian and his team of dedicated construction loan officers:
1. Prequalification and Loan Application
Submit a loan application along with income documentation, tax returns, asset statements, and credit information. Your lender reviews your debt-to-income ratio, credit score, and overall borrowing capacity to determine your maximum loan amount and the best program for you.
2. Builder, Plans, and Budget Review
Your builder or contractor must be approved and licensed in North Carolina. You'll submit signed builder contracts, full plans, a complete construction budget, and a project timeline. The lender will order an "as-completed" appraisal based on those documents.
3. One Closing, One Locked Rate
You close once. Your interest rate is locked, the land is funded if you don't already own it, and construction can begin. There's no requalifying later and no second closing on the horizon.
4. Construction Draws and Inspections
Funds are released to your contractor on a draw schedule — typically four to six draws — with inspections to verify progress. During the construction phase, you make interest only payments on the funds drawn so far, which keeps the short term cost manageable while the house is being built.
5. The Loan Converts Automatically to Permanent Financing
When construction is complete, the loan converts automatically to permanent financing at the rate you locked at closing. No second closing, no second appraisal, no second set of costs — just a smooth transition into your permanent mortgage on move in day.
Loan Programs for New Construction in Wake Forest
One of the biggest benefits of working with a specialist is access to multiple home construction loans. Wake Forest borrowers most often qualify for:
- Conventional Single Close Construction Loan — Flexible terms for borrowers with strong credit and a down payment.
- VA Loans (Single Close) — A powerful option for veterans and active-duty service members. Zero down payment, no PMI, and competitive VA interest rates.
- FHA Construction to Permanent Loan — Lower credit minimum thresholds and as little as 3.5% down.
- USDA Single Close Construction Loan — Available in qualifying rural areas around Wake Forest, Youngsville, and Rolesville. Zero down payment for eligible borrowers.
- Manufactured and Modular Home Construction Loans — Programs designed for modular and manufactured builds on owned land.
If you'd rather renovate an existing home than build from scratch, Bob can also discuss renovation financing — but if your goal is a true new home, a single close program is almost always the best fit.
Who Qualifies for a Single Close Construction Loan?
Each program has its own thresholds, but most Wake Forest borrowers will need:
- A credit score that meets the program's minimum (often mid-600s or higher)
- Documented, stable income and a manageable debt-to-income ratio
- A signed builder contract with a licensed North Carolina contractor
- Complete plans, specs, and a line-item construction budget
- A down payment that meets the program's loan-to-value requirements
- Homeowners insurance and builder's risk insurance bound at closing
- Funds or land equity for the lot
If you already own your land, that equity often counts toward your down payment — a major advantage for buyers who purchased the parcel before deciding to build. Borrowers who plan to sell their current home can also discuss bridge strategies that align with their build timeline.
Frequently Asked Questions
How long does construction typically take?
Most custom homes in Wake Forest take 9 to 14 months from groundbreaking to certificate of occupancy. Your loan terms will allow for a construction window that fits this timeline, with extensions available if needed.
Can I roll the cost of the land into the loan?
Yes. A single close construction loan in Wake Forest, NC can finance the land purchase, soft costs, and the build itself in one loan.
Do I make payments during construction?
You'll typically make interest only payments on the amount drawn during the construction phase. Full principal-and-interest payments begin once the loan converts to permanent financing.
What if construction goes over budget?
A contingency reserve is usually built into the loan to cover modest overruns. For larger changes, a change order process keeps everyone aligned.
Start Building Your Wake Forest Dream Home with Bob Fabian
A single close construction loan in Wake Forest, NC is the simplest, most predictable way to finance a custom home — and choosing a lender who specializes in new construction makes all the difference. Bob Fabian and his dedicated construction loan officers have guided more than 1,500 borrowers through the financing process, with a focused expertise in one time close loans, construction to permanent loans, and VA loans across North Carolina.
Ready to make your dream home a reality in Wake Forest, Rolesville, or Youngsville? Contact Bob Fabian today to discuss your plans, your land, and the program that fits your life best — and to begin the loan approval process for the next chapter of your future.