Build Your Dream Home with a Single Close Construction Loan in Pleasant Prairie, WI
Understanding Single Close Construction Loans
A single close construction loan—also called a construction‑to‑permanent loan—wraps your short‑term construction financing and permanent mortgage into one convenient loan. You close once, saving time and closing costs, and your rate and terms are set from the start. When your home is complete, your loan automatically converts into long-term permanent financing.
Why Pleasant Prairie Is Perfect for Building
Pleasant Prairie, WI is known for its beautiful neighborhoods, scenic lots, and strong community amenities. If you’ve found the ideal spot for your dream home, this area offers both open land and established developments to start building in confidence. Whether you’re upgrading from your current home or planning your first single-family house, the market supports smart financing opportunities.
How the Construction Process Works
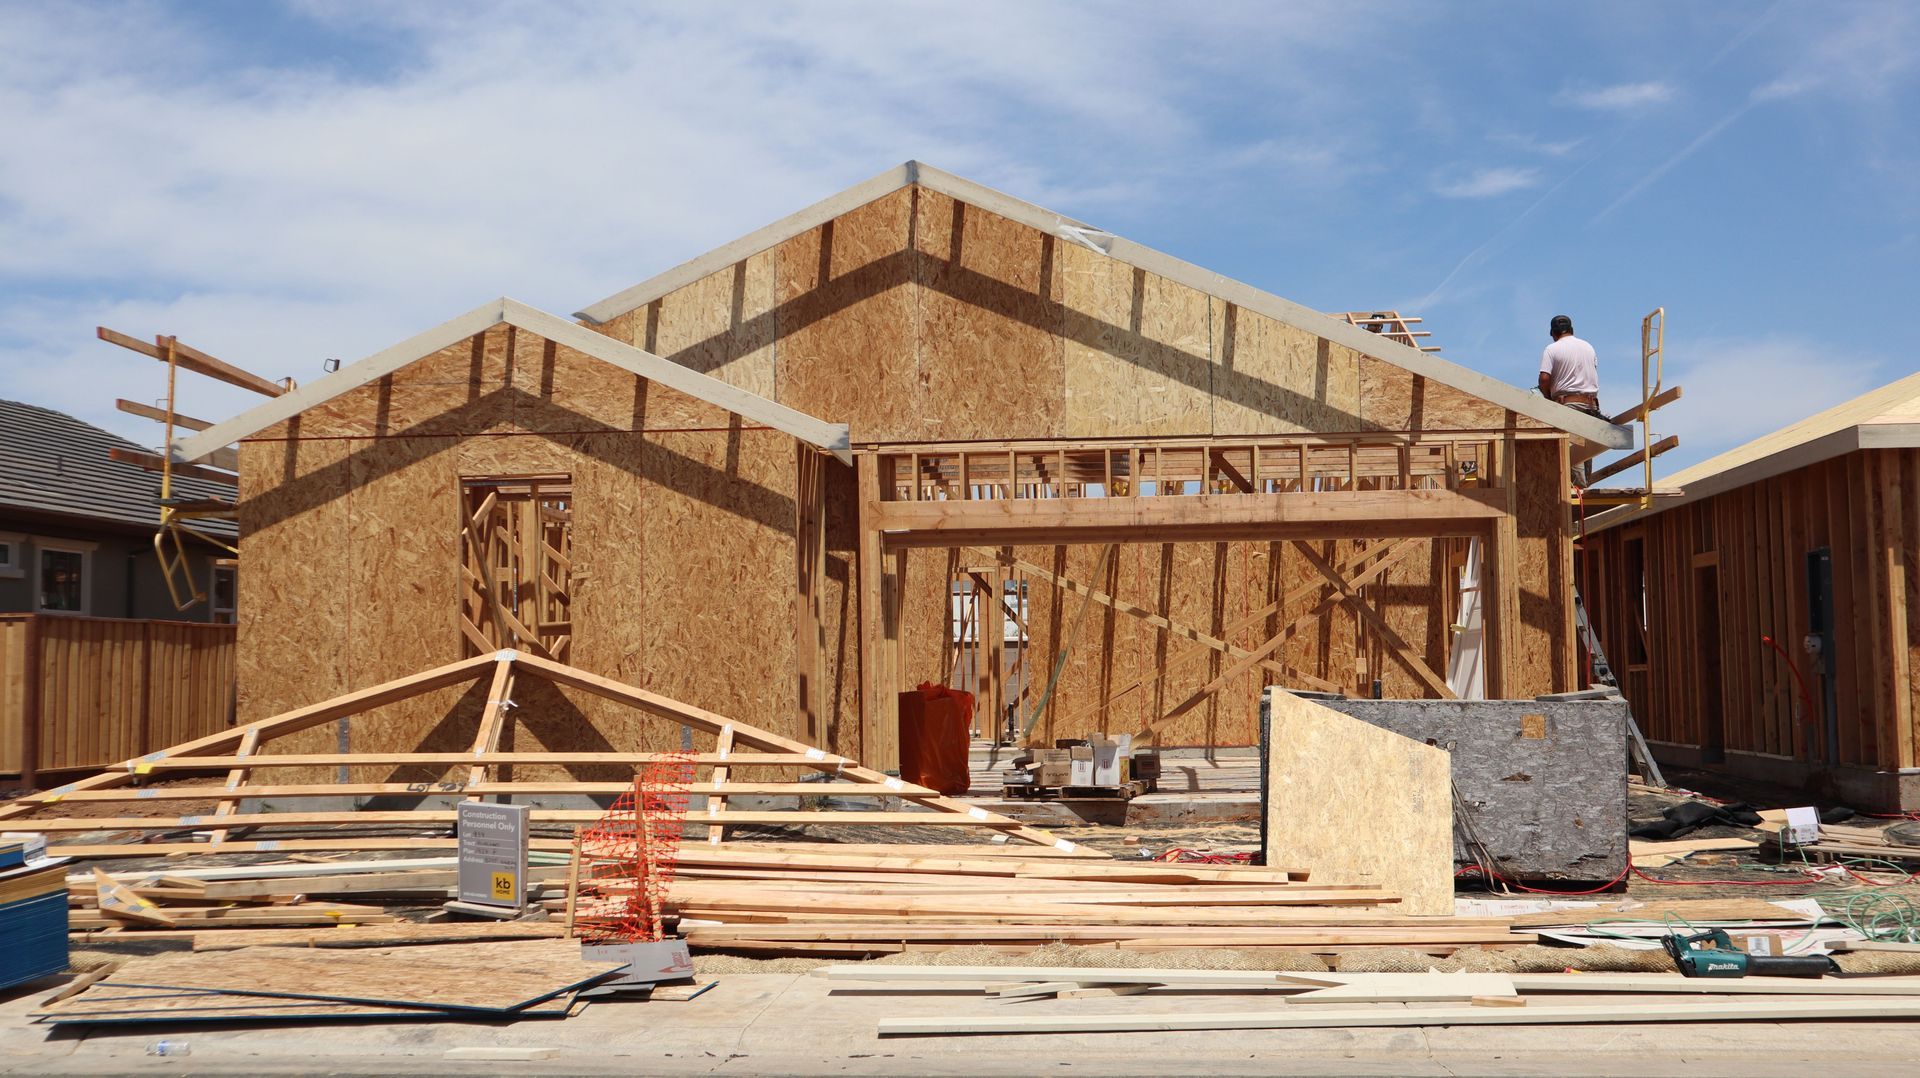
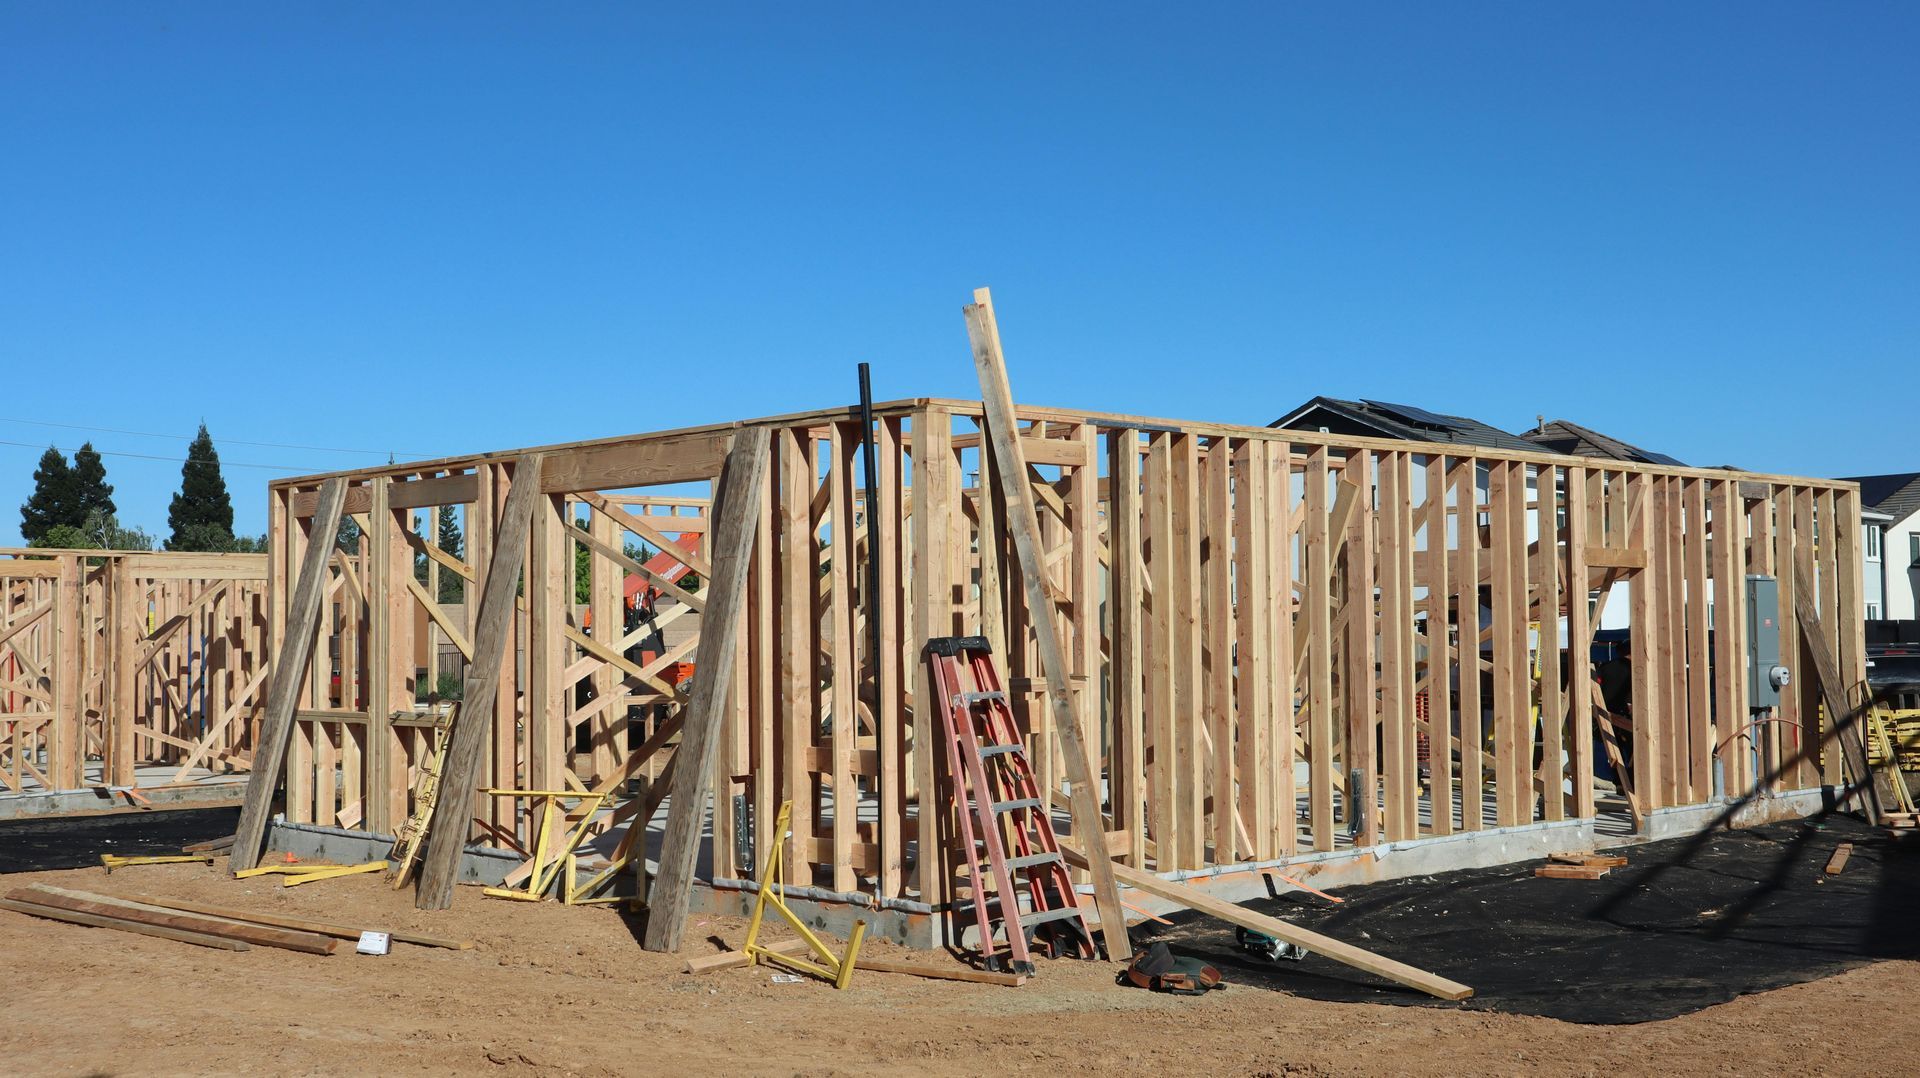
The construction process begins with credit approval, a review of your plans, and confirmation of your builder and budget. During the construction phase, the loan funds are released in stages as your home progresses—from pouring the foundation to the final inspection. This structure ensures funds are available when needed without overspending early.
Benefits of a Single Close Loan
- One closing instead of two separate ones
- Locked-in interest rate before construction begins
- Simplified paperwork and fewer fees
- Protection from changing market conditions
- Smooth conversion into your permanent loan at completion

Interest‑Only Payments During Construction
While your home is being built, you’ll make interest‑only payments based on the amount already disbursed. This keeps your monthly payment low during the construction period. Once your home is complete, your monthly mortgage payment automatically shifts to cover principal, interest, and property taxes.
Down Payment and Loan Requirements
Most construction loans require a down payment, typically between 5% and 20%, depending on your loan program and credit approval. Some borrowers even use home equity loans or lot loans toward their lot purchase or initial costs. Working closely with your loan officer ensures your strategy fits your financial picture and long‑term plans.
Managing Costs and Closing Expenses
With a single close, you’ll only pay closing costs once. This helps you save compared to traditional loans requiring separate closings for construction and mortgage. Ask your lender or loan officer about options to roll some costs into the loan amount to reduce upfront out‑of‑pocket expense.
Building Process and Final Inspection
Your lender will work with your builder to track milestones throughout construction. After each phase, inspections confirm the work meets approved project details. At the end, a final inspection and appraisal verify that your new home is complete and ready for occupancy before the loan transitions to your permanent mortgage.

Competitive Rates and Flexible Terms
Pleasant Prairie borrowers can expect competitive rates, flexible loan terms, and various loan options to match their goals. Locking in a fixed rate before construction helps protect against rate changes and supports affordable monthly payments once your mortgage becomes permanent.
Planning for Taxes and Payments
Remember that your monthly mortgage payment after completion will include principal, interest, and property taxes (and possibly private mortgage insurance, if required). Understanding these combined payment amounts ahead of time helps you plan your budget more effectively.
Qualifying and Getting Approved
To qualify, lenders evaluate your income, credit, property, and plans. Detailed estimates from your builder and a clear budget help the approval process run smoothly. Each application is subject to credit approval, so it’s important to work with a loan officer who can anticipate questions and guide you through every requirement.
Choosing the Right Loan Officer in Pleasant Prairie
Selecting a knowledgeable loan officer ensures your construction financing moves forward without surprises. They’ll answer common questions, explain interest payments, and help you decide between different loan options based on your timeline, budget, and dream home vision.
Contact Bob Fabian to Start Building
Ready to build your dream home in Pleasant Prairie, WI? Contact Bob Fabian today for personalized guidance on single close construction loans, lot financing, and permanent mortgage solutions. With years of local lending experience, Bob and his team offer secure, streamlined support—helping turn your plans into a completed new home you’ll love for years to come.