Building Your Dream Home in New Concord: The Advantages of Single Close Construction Loans
Hello, I'm Bob Fabian, a loan officer dedicated to making homeownership dreams a reality for families and individuals across Ohio. With a focus on single close construction loans, I've helped many clients build their ideal homes in charming communities like New Concord. This welcoming village in Muskingum County, home to around 2,300 residents, offers a tight-knit community feel, rich history, and the vibrant energy of Muskingum University.
Known as the boyhood home of astronaut John Glenn, New Concord blends small-town tranquility with cultural attractions, including campus events, music performances by the Southeastern Ohio Symphony Orchestra, and historic sites tied to its Presbyterian roots and the old National Road. Whether you're drawn to the rolling hills, family-friendly atmosphere, or proximity to nearby Cambridge and Zanesville, New Concord is a wonderful place to put down roots and create your dream home.
What Are Single Close Construction Loans?
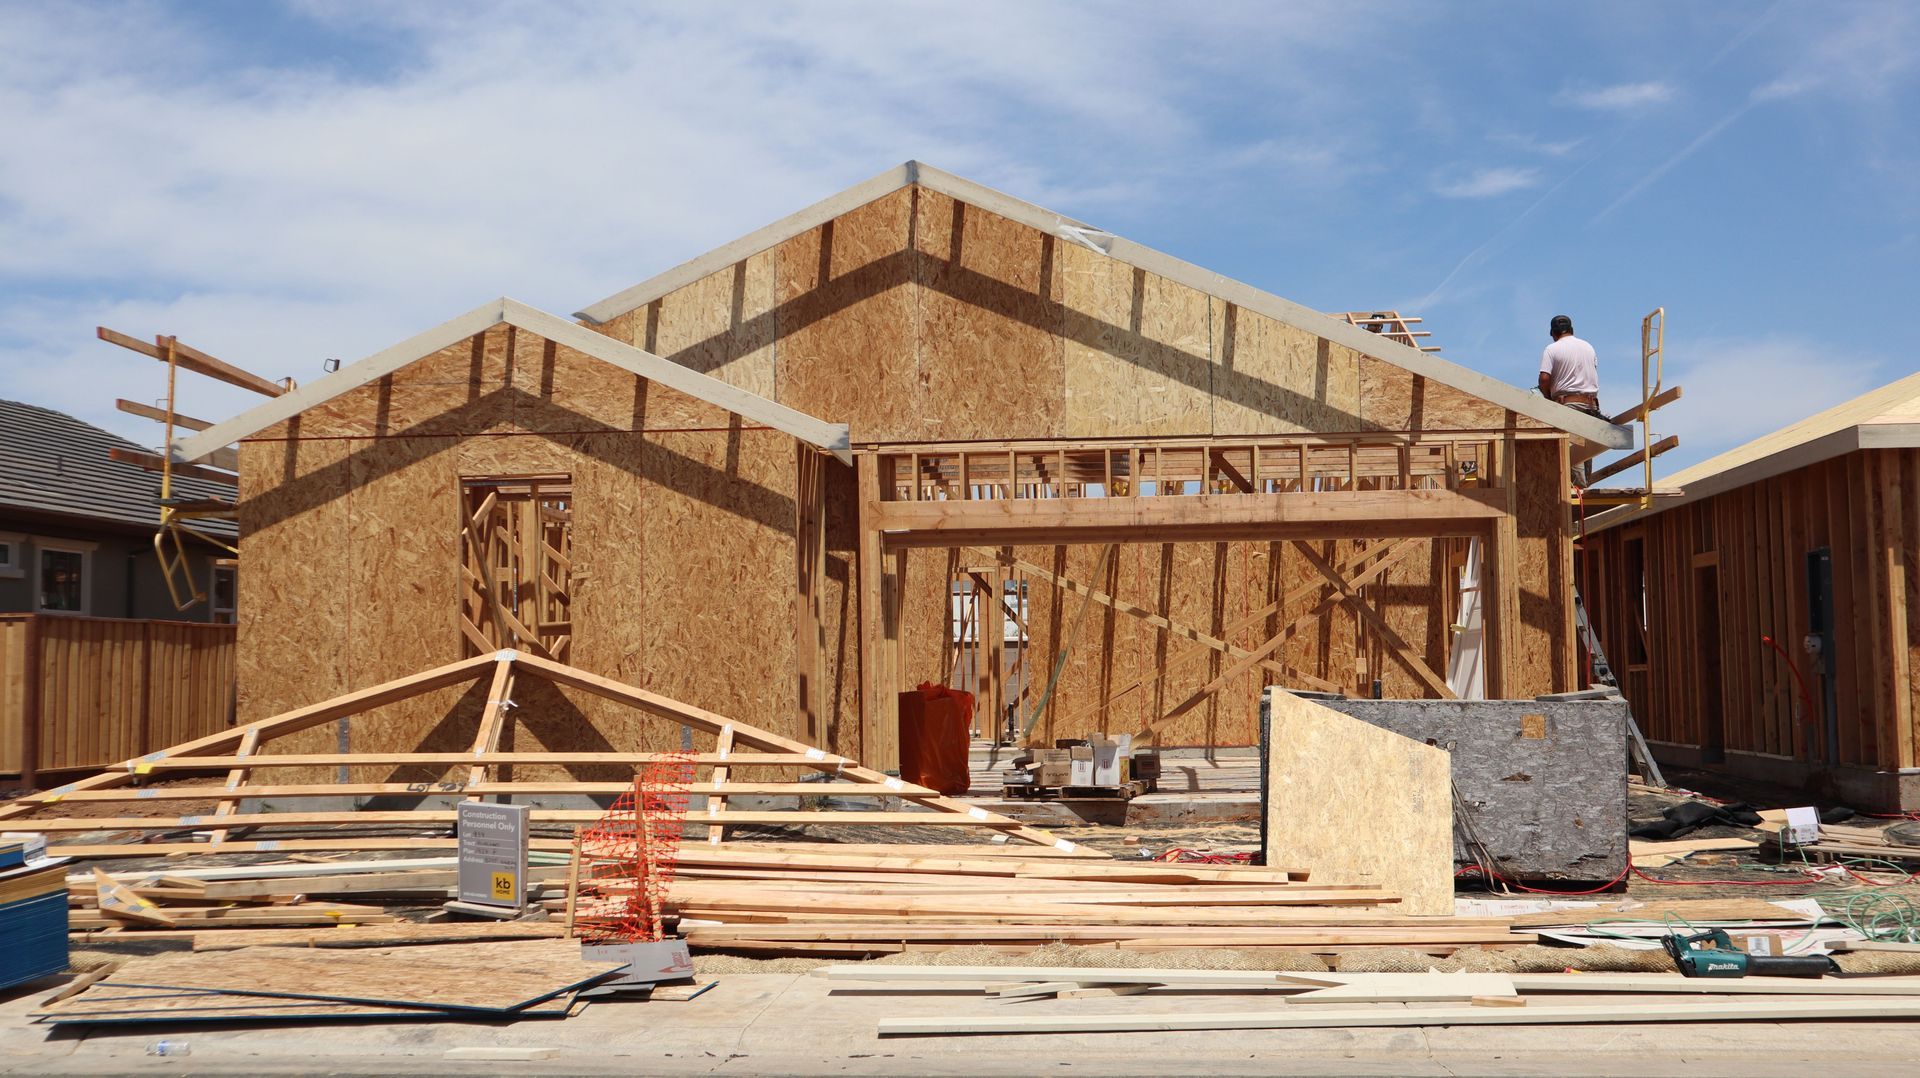
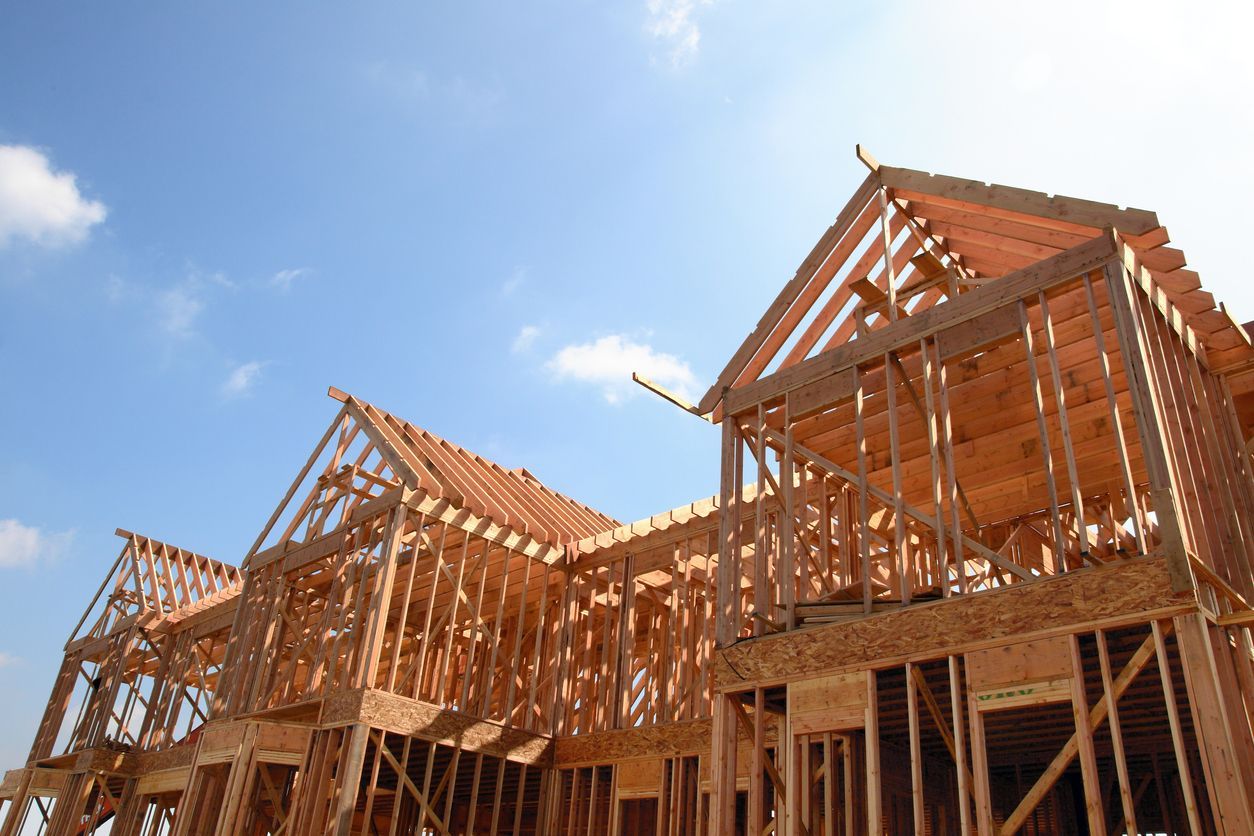
Planning new construction in New Concord? Traditional financing often requires separate loans—one for the construction phase and another for the permanent mortgage. This means multiple closings, higher overall costs, and the stress of requalifying later. Single close construction loans, also called one-time close loans, simplify everything by combining both into one loan program.
You close once at the start, securing your interest rates upfront. The loan can cover land acquisition (if you're buying property), construction costs, and transition seamlessly into a long-term mortgage once the build is complete. Funds are released in stages to keep your project on budget, and payments during construction are sometimes interest-only on the drawn amount—making it easier to manage while building your house.
In rural and suburban areas like New Concord, options such as FHA or USDA-backed single close loans are particularly popular. FHA programs allow for lower down payments and more flexible credit requirements, while USDA loans can offer 100% financing for eligible rural properties, with no down payment required for qualified borrowers.

Why Choose Single Close Loans in New Concord?
New Concord's appeal lies in its strong sense of community, excellent schools, and access to outdoor recreation amid Ohio's beautiful landscapes. Building here means enjoying university events, local history, and a peaceful village life—all while being conveniently located along I-70. Single close construction loans align perfectly with this lifestyle by offering:
- Streamlined Process: One application and closing reduce paperwork and time. Provide your financial details upfront, and focus on designing your dream home without worrying about mid-project refinancing.
- Cost Savings: Avoid duplicate closing fees and protect against rising interest rates during construction. This is especially valuable in today's market, helping you afford more of the features you want in your new home.
- Flexible Options: Programs like FHA suit first-time buyers or those with moderate credit, while USDA is ideal for New Concord's rural-eligible areas, often with competitive rates and no private mortgage insurance.
- Ease for Borrowers: Lower minimum down payments, interest-only payments during the build, and support for working with local builders make it accessible for families, young professionals, and retirees investing in the community.
Compared to separate loans, this approach minimizes risk and lets you enjoy the fun parts of building—like choosing finishes for a home with views of the surrounding hills or space for family gatherings.
Qualifying and Getting Started
To qualify in New Concord, you'll typically need a stable income, decent credit (often starting around 580-640 depending on the program), and plans from a licensed builder. USDA options shine here for rural development, allowing borrowers to secure financing that covers the entire project without a large upfront investment.
If building in this historic and vibrant Ohio village sounds like the right step for you—whether near Muskingum University's scenic campus or on a quiet lot with room to grow—single close construction loans can turn that vision into reality without unnecessary complications.
Let's Connect and Build Your Future
As a loan officer who strives to put customers' priorities first, I'm here to answer your questions, review loan options, and guide you through every step of the process. Whether you're ready to start submitting plans or just exploring how to afford your dream home in New Concord, contact me, Bob Fabian, today for a personalized consultation. Reach out by phone or through my site—let's make homeownership in this wonderful community your next achievement!