Building Your Dream Home in Waukesha: Explore Single Close Construction Loans
Hello, I'm Bob Fabian, a loan officer committed to helping Wisconsin families secure the financing they need to build their ideal homes. With expertise in single close construction loans, I've supported many clients in vibrant communities like Waukesha. Just 15 miles west of Milwaukee along the scenic Fox River, Waukesha is a thriving city of around 71,000 residents, blending historic charm with modern appeal. Nicknamed "Spring City" for its famous healing springs in the 19th century and "Guitartown" for its vibrant music scene, Waukesha boasts a lively historic downtown with concerts, farmers markets, the scenic Riverwalk, festivals, excellent schools, award-winning parks, and family-friendly neighborhoods.
Proximity to Milwaukee makes it perfect for commuters, while its rich history—including landmarks like the Old Waukesha County Courthouse and Queen Anne architecture—adds timeless character. Whether you're eyeing a spot near the Fox River or in a quiet suburban enclave, Waukesha offers an exceptional setting for new construction.

The Power of Single Close Construction Loans
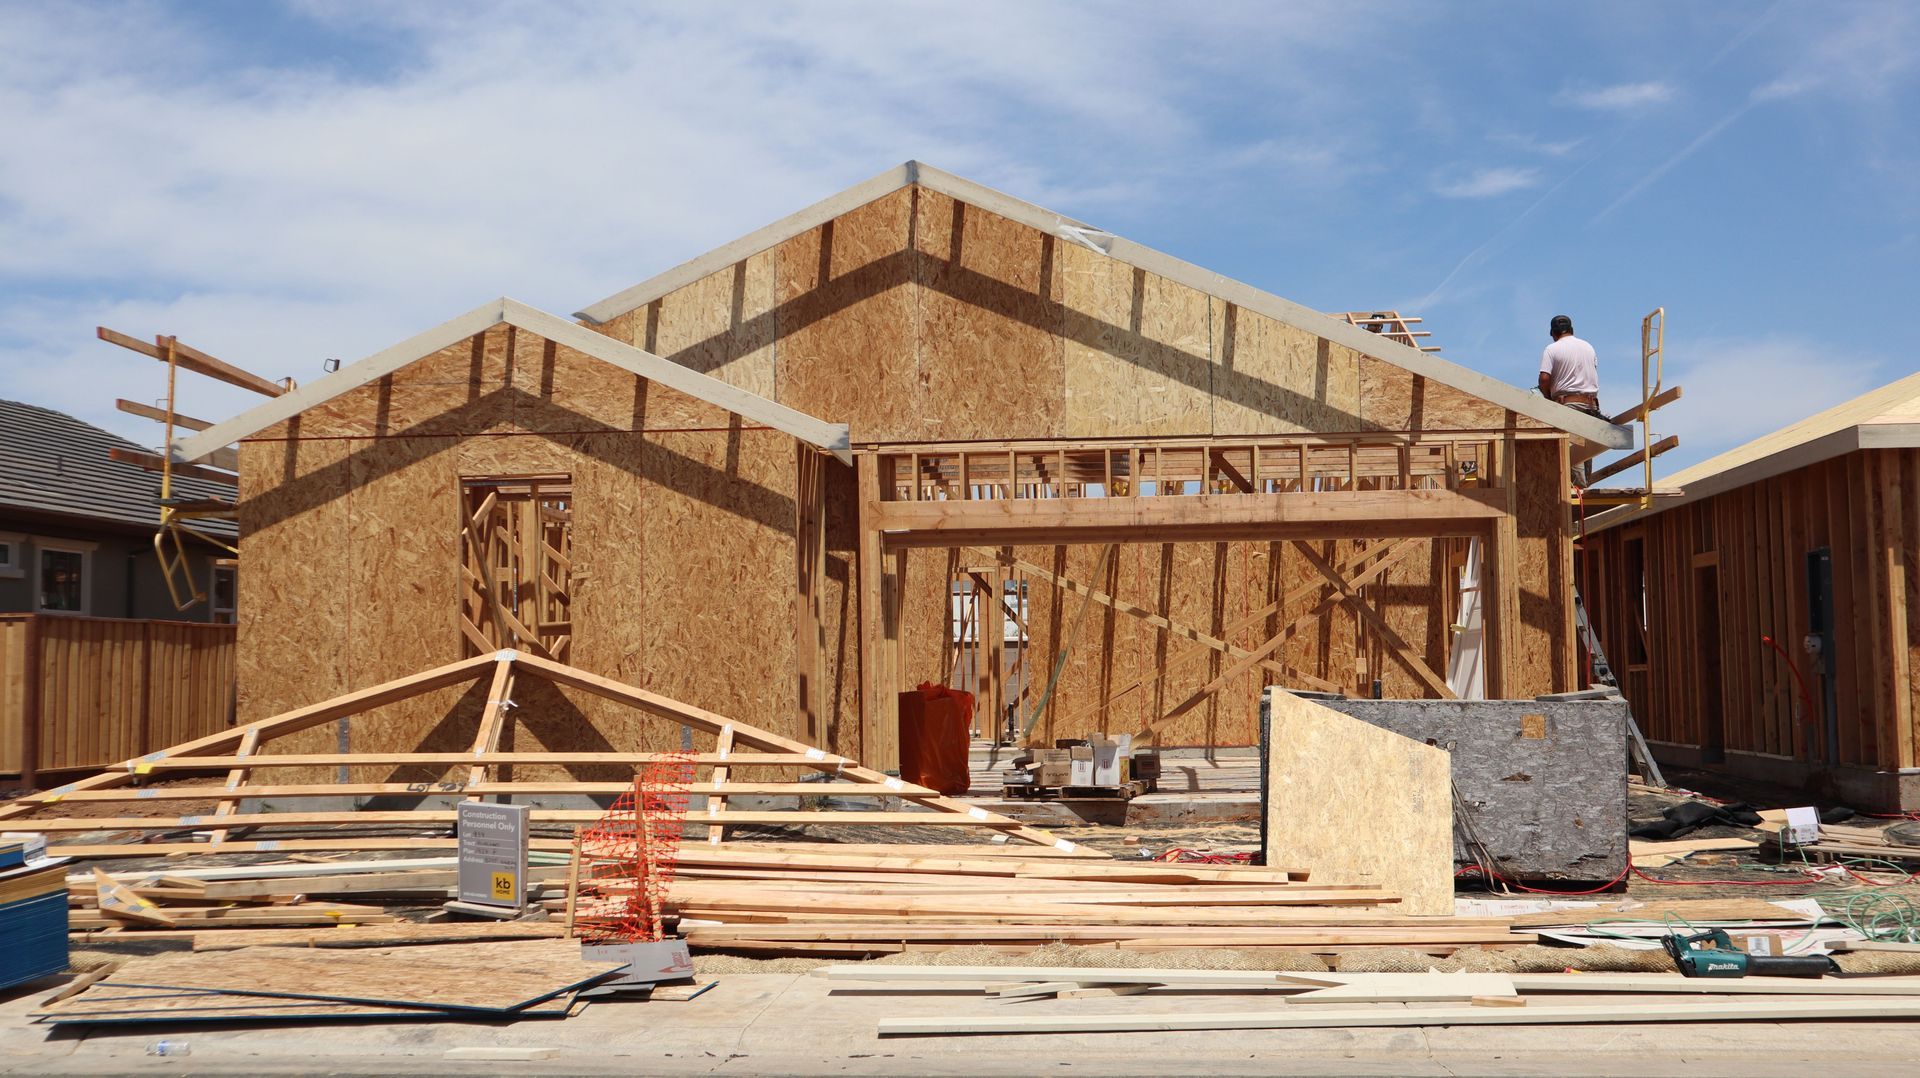
Building a new home in Waukesha? Traditional options often split financing into separate loans: one for construction and another for the permanent mortgage. This leads to multiple closings, extra fees, and uncertainty with interest rates. Single close construction loans—also called one-time close loans—simplify it all by combining everything into one mortgage loan from the beginning.
You close once upfront, securing your interest rate early and covering land purchase (if needed), construction costs, and fees. Funds are disbursed in stages as your project progresses, with interest-only payments during the construction phase to keep monthly costs manageable. Once the home is complete and meets quality standards, the loan automatically converts to your long-term mortgage—no second closing required.
In Wisconsin, single close options include flexible programs like FHA for lower down payments and credit guidelines, VA for eligible active military and veterans (often with no down payment), and conventional backed by Fannie Mae for those seeking competitive terms. These make building more accessible, especially in growing areas like Waukesha where property values and demand are strong.
Why Single Close Loans Fit Waukesha Perfectly
Waukesha's mix of urban conveniences and suburban tranquility—complete with riverfront parks, historic sites, and easy access to Milwaukee—makes it a top choice for families building custom homes. Single close loans align with this lifestyle by delivering key benefits:
- Lower Overall Costs and Savings: One closing means avoiding duplicate closing costs, appraisals, and fees—potentially saving thousands to invest in premium features or upgrades for your new home.
- Secure Financing Early: Lock in your interest rate at the start to protect against fluctuations, giving you peace of mind throughout the build timeline.
- Flexible Options for Buyers: FHA offers lower down payments (as low as 3.5%) and helps those with moderate credit qualify. VA provides maximum benefits for service members, while Fannie Mae-backed conventional loans suit a wide range of borrowers. This variety helps more families afford their dream home without stretching the budget.
- Streamlined Process: Less paperwork, no mid-project requalification, and built-in tracking of funds ensure your construction project stays on schedule and within budget. Work with a reputable builder, and focus on the excitement of designing your space.
Compared to separate loans, single close reduces complexity and risk, letting you enjoy Waukesha life sooner—whether strolling the Riverwalk, attending downtown events, or settling into a family-oriented neighborhood.

Qualifying and Next Steps in Waukesha
Qualification typically involves stable income, a solid credit profile, and approved plans from a licensed builder. Programs vary: FHA and VA often have more lenient requirements, while conventional may need higher credit for the best rates. In Waukesha's competitive market, these loans help buyers act quickly on desirable land or lots.
If you're ready to build in this dynamic Wisconsin city—perhaps a modern family home with views of the Fox River or space for kids and gatherings—single close construction loans make it straightforward and cost-effective.
Let's Make Your Waukesha Dream a Reality
As a dedicated loan officer, my top priority is guiding you through every step with clear options and personalized support. Whether you have questions about qualifying, current interest rates, down payments, or tailoring a loan to your construction project, I'm here to help. Contact me, Bob Fabian, today for a no-obligation consultation. Let's connect and get started on building the home and life you've always wanted in Waukesha!