Purchase Price vs. Total Cost: The Math Nobody Shows You in Wisconsin
A buyer in Wisconsin recently told Bob Fabian he'd found "the deal of the century" a resale home $40,000 under builder pricing in the same neighborhood. Eighteen months later, that same buyer was replacing a furnace mid January and residing a house that looked fine at closing but wasn't built for what a Wisconsin winter actually does to a home.
That's the story Bob Fabian tells clients when they ask him whether building is "worth the extra money." It usually isn't the extra money people think it is. It's just money that shows up at a different time.
Why Purchase Price Is the Wrong Starting Point
Purchase price is the easiest number to compare, which is exactly why it's the number most buyers anchor on. But comparing purchase price alone is like comparing two used cars by sticker price without asking about the engine. Bob Fabian, a mortgage originator at Sistar Mortgage, works with buyers on both sides of this decision every week, and the pattern is consistent: the home with the lower purchase price rarely stays the cheaper option for long.
What Wisconsin Winters Add to the Equation
Wisconsin buyers carry a cost variable that milder climates don't: heating season. Older resale homes often carry outdated insulation, aging furnaces, and windows that were adequate in 1995 but leak heat badly by today's standards. New construction is typically built to current energy codes, which means lower monthly utility costs for years. That's not a cosmetic upgrade it's a recurring line item that compounds every winter a buyer owns the home.
The Real Comparison: Total Cost, Not Sticker Price
Total cost includes the purchase price, plus financing terms, plus what the home will actually cost to live in and maintain over the next 5 to 10 years. Roof age, HVAC age, insulation quality, and change orders on a new build all belong in that math not just the number on the offer sheet. Bob Fabian walks buyers through this comparison directly, because a lender who only talks about the loan amount isn't giving the full picture of what a buyer is signing up for.
Where Change Orders and Lot Premiums Actually Fit In
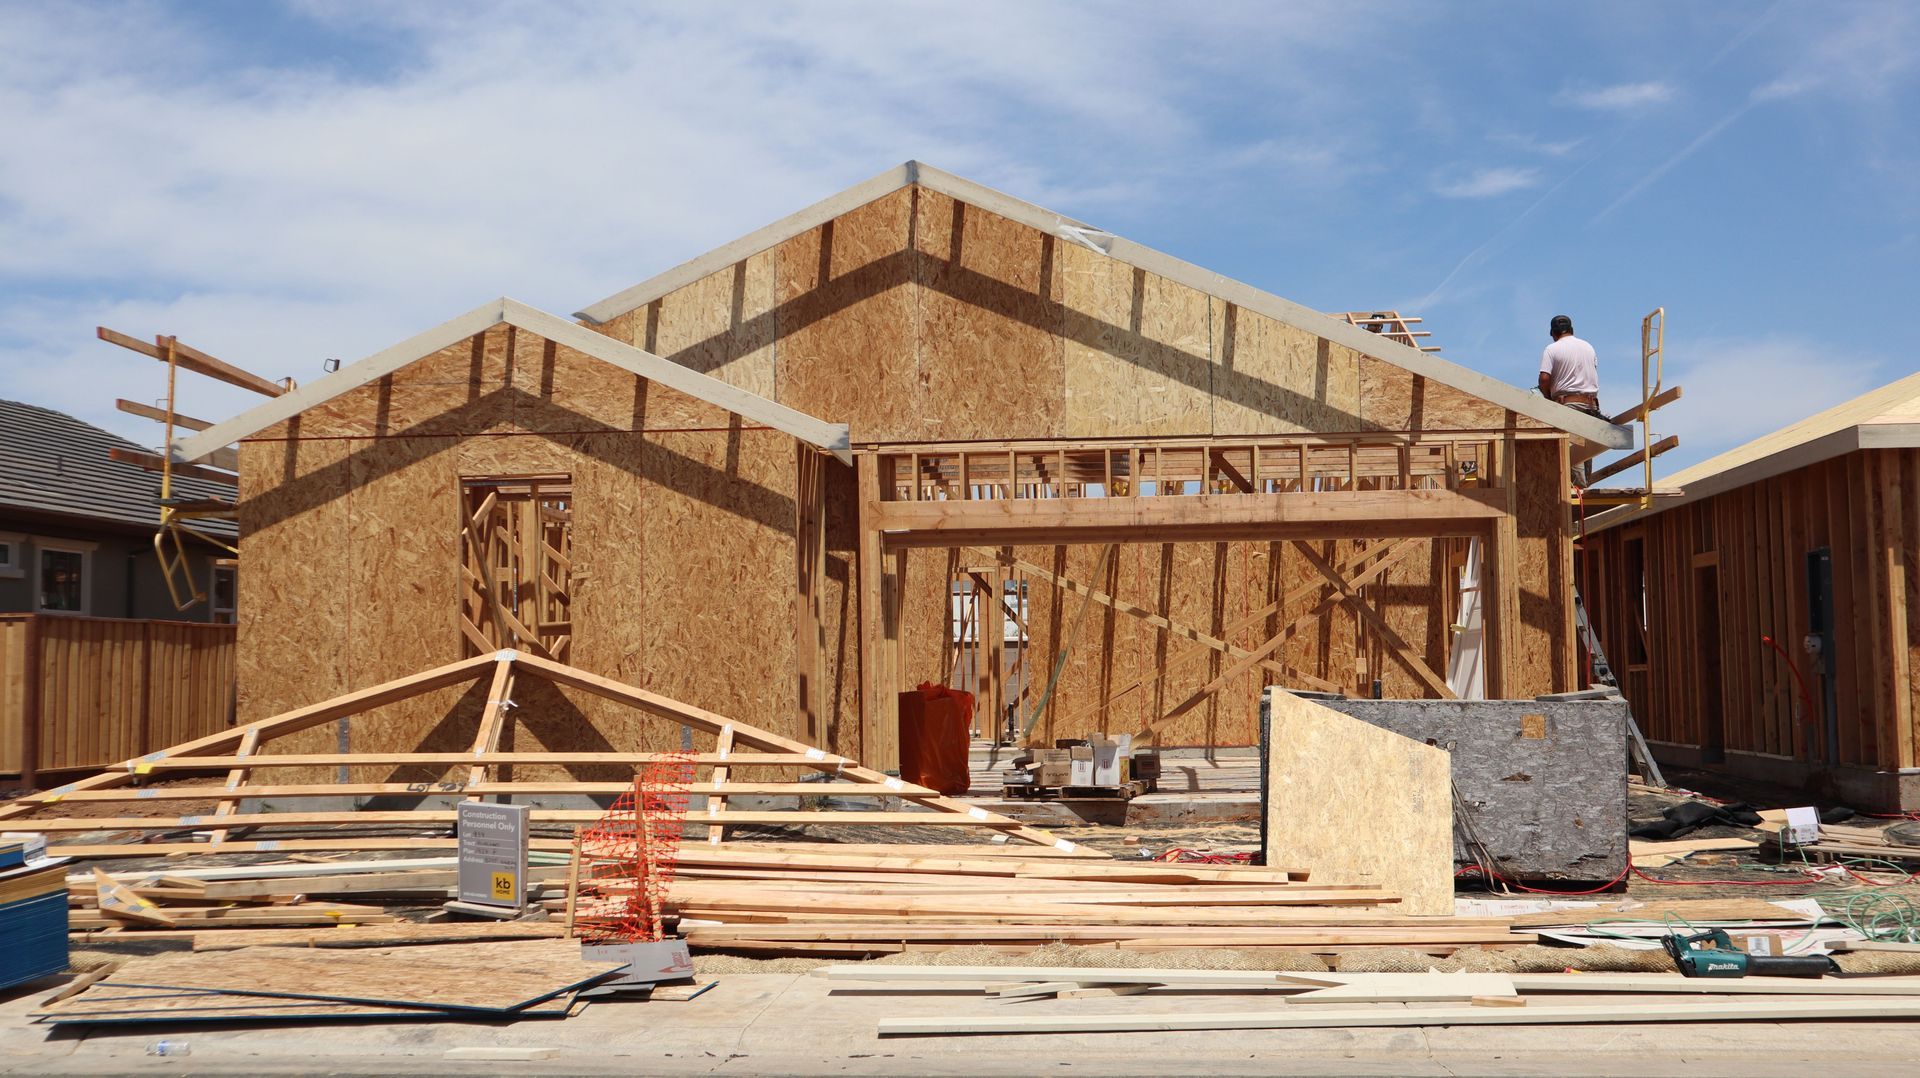
New construction does come with costs resale doesn't: lot premiums, upgraded finishes, and change orders during the build. These are real, and Bob Fabian doesn't sugarcoat them with clients. But these costs buy something specific control over layout, finishes, and systems from day one, instead of inheriting someone else's decisions and someone else's deferred maintenance.
Land Equity Can Change the Math Again
For Wisconsin buyers who already own land or have equity built up in a property, that equity can often be applied toward the down payment on a construction loan, reducing the cash needed upfront. This is one of the more overlooked levers in the build vs buy decision, and it's a conversation Bob Fabian has regularly with clients who assume building requires more cash on hand than buying does. Sometimes it requires less.

The Question Bob Fabian Asks Every Client
Bob Fabian doesn't ask clients "can you afford this house." He asks, "what are you actually paying for?" A lower purchase price that comes with a furnace replacement in year two isn't actually cheaper. A higher purchase price that comes with fewer surprises, lower utility bills, and a home built for Wisconsin winters might be the better financial decision, even though it doesn't look that way on the offer sheet.
Getting the Full Picture Before You Decide
Buyers don't need to choose between building and buying based on price alone they need someone to run the actual numbers on both paths. That's the role Bob Fabian plays: not selecting the builder, not managing the construction, but making sure the financing and the total cost comparison are clear before a buyer commits either way. If you're weighing a resale purchase against building in Wisconsin, that's a conversation worth having before you sign anything.