Simplify Your Build with a Single Close Construction Loan in Kenosha, WI

If you’ve been searching for an easier way to finance your new home construction in Kenosha, WI, a single close construction loan could be exactly what you need. This convenient loan program combines both the construction and permanent financing into one closing, helping you manage costs, reduce risk, and stay on track from groundbreaking to move-in day.


What Is a Single Close Construction Loan?

Traditionally, building a new home involves two separate loans—one for construction and another for the permanent mortgage once the home is complete. With a single close construction loan, you only go through one closing process, one set of fees, and one credit approval. The loan automatically converts into your long-term mortgage after the final inspection, eliminating the need to refinance later.


This program simplifies documentation, reduces overall closing costs, and offers you more control over your project’s finances. Some lenders even allow borrowers to lock in interest rates upfront, adding security against market fluctuations during the construction phase.

APPLY NOW!
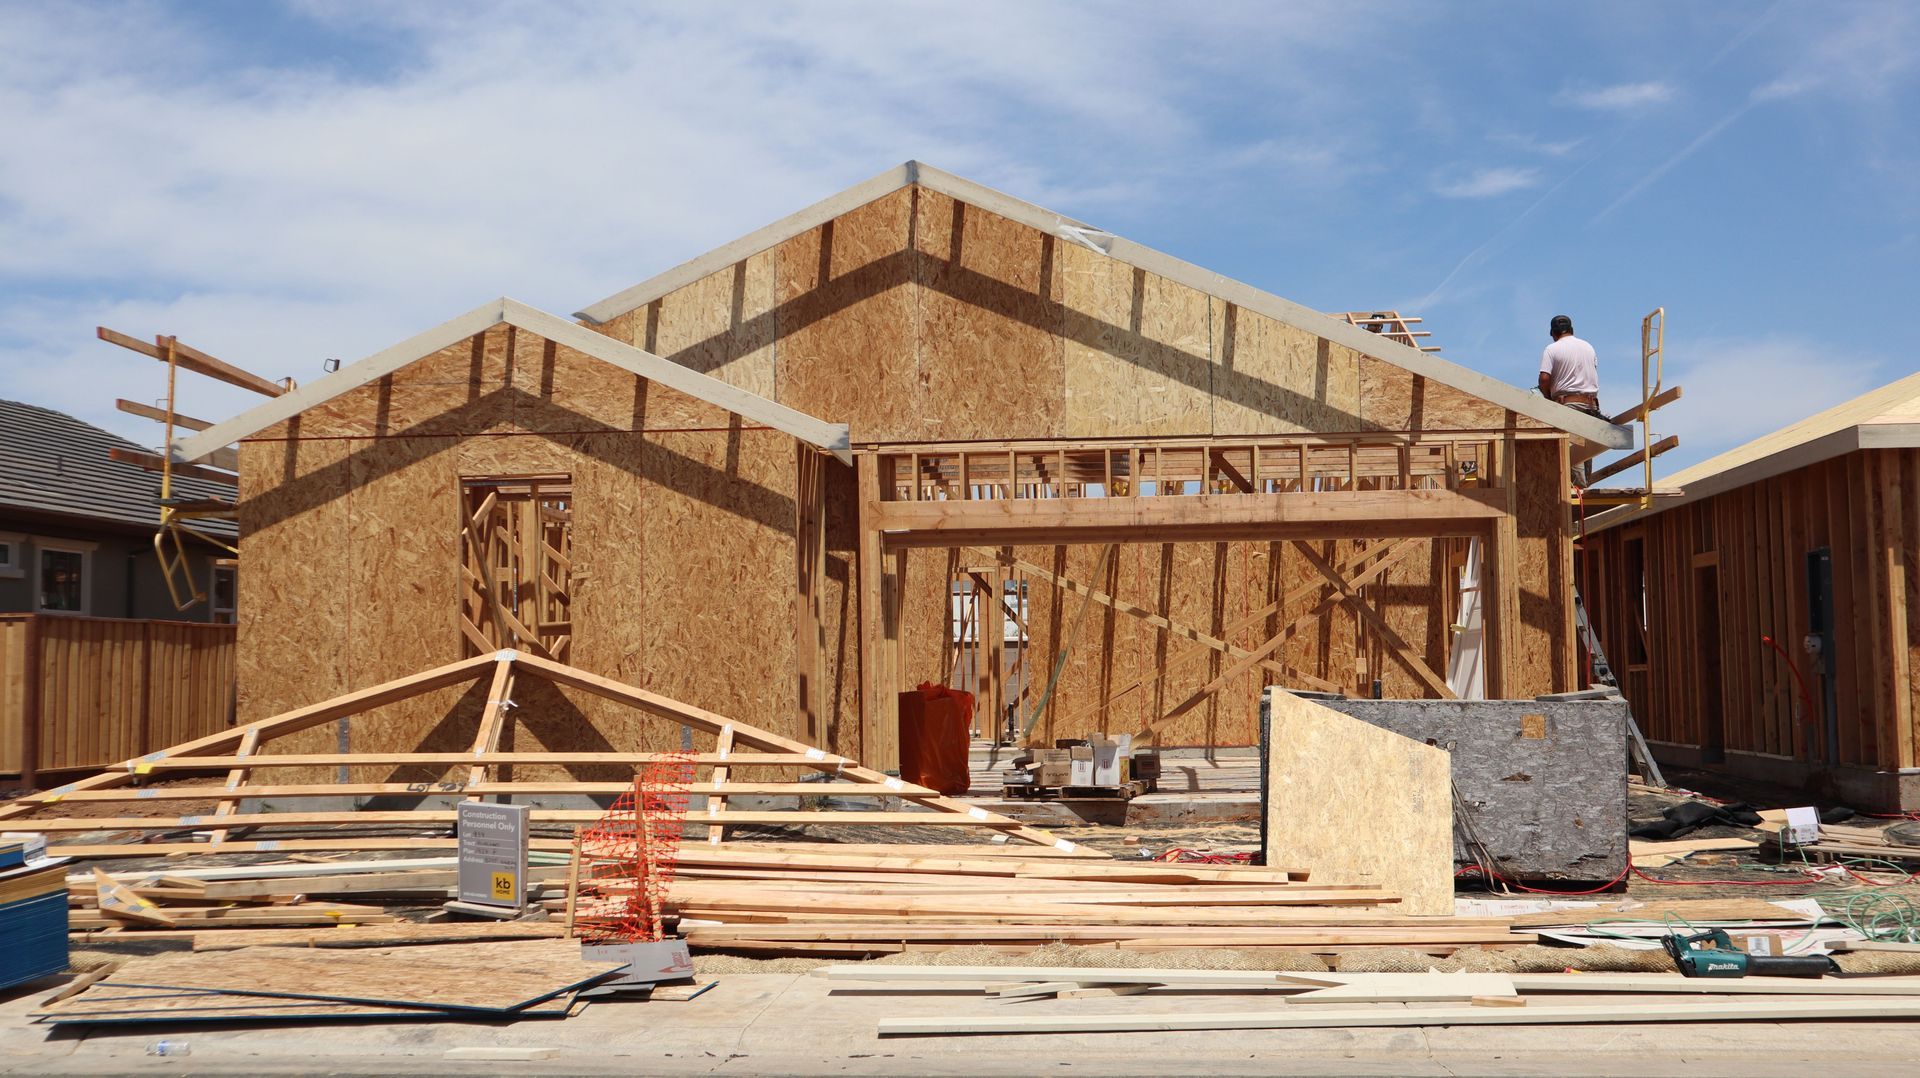
House under construction; wood frame visible, red dumpster, orange safety barriers.

Why Kenosha Homebuilders Prefer Single Close Construction Loans

Kenosha’s market—set along beautiful Lake Michigan and rich with community landmarks like the Kenosha History Center and Kenosha Public Museum—has become an ideal spot for new family homes and investments. Whether you’re planning a modern lakeside home or a charming starter house in Kenosha County, a single close construction loan helps make that dream home a reality.


Key advantages include:

  • One-time closing: Fewer transactions, less paperwork, and reduced costs.
  • Locked-in interest rates: Secures your rate during both construction and permanent phases.
  • Simplified payments: You make interest-only payments during construction, then transition to your regular mortgage schedule.
  • Reduced risk: Your financing is fully in place before construction begins, creating confidence for both you and your builder.


How the Process Works

  1. Planning & builder approval: Work with your builder to finalize contracts, construction plans, and pricing details.
  2. Application & underwriting: Your lender reviews credit, budget, and project documentation to determine eligibility.
  3. Closing: Once approved, you sign one set of loan documents and close on both the construction and permanent loan.
  4. Construction phase: Funds are released in stages through draws as work progresses, from site prep to final completion.
  5. Conversion to permanent financing: After your final inspection, your loan automatically converts to a traditional mortgage—no need for another closing.
APPLY NOW!
Man sits on wooden beam, looking at nail gun. Building a wooden structure in sunlight.

Loan Options to Fit Your Needs

Borrowers in Kenosha County can explore a variety of construction loan options, including conventional and FHA single close loan programs, each suited to different budgets and credit profiles. Whether your goal is a family home near downtown Kenosha or a custom build overlooking the lake, there’s a program designed to keep your project financially efficient and secure.


Build Your Dream Home in Kenosha

Home construction doesn’t have to mean juggling multiple loans or worrying about changing interest rates. With the right lender and a single close construction loan, you can manage expenses, keep your timeline on track, and enjoy a seamless journey to homeownership.

APPLY NOW!
Wooden house under construction against a cloudy sky. Lumber and framing visible.
Wisconsin couple reviewing new construction blueprints at a job site, planning how much cash they ne
By Bob Fabian • October 30, 2026
How much cash do you need to buy a new construction home in Wisconsin? Beyond the down payment, plan for closing costs, earnest money, and reserves. See your options.
Wisconsin home under construction with worker reviewing blueprints, illustrating locking a mortgage
By Bob Fabian • October 30, 2026
Lock your mortgage rate on a new construction home before the build starts. Learn how construction loan rate locks work in Wisconsin and what to expect. Learn more.
Wisconsin homeowner reviewing construction loan closing cost documents inside a newly framed home wi
By Bob Fabian • October 30, 2026
Construction loan closing costs in Wisconsin run 2–5% of the loan amount, paid once. See what's included, what you can negotiate, and how to compare estimates.
Wisconsin home under construction with wood framing on a rural lot, illustrating single-close constr
By Bob Fabian • October 30, 2026
VA and USDA single-close construction loans let Wisconsin buyers build with $0 down. FHA requires just 3.5%. Compare your options and get started today.
First-time buyers reviewing blueprints on a Wisconsin lot, considering a single-close construction
By Bob Fabian • October 23, 2026
First-time homebuyers in Wisconsin can qualify for single-close construction loans with as little as 3.5% down. Learn how prequalification works. Get started.
Wisconsin homebuyer reviewing a single-close construction loan lender comparison document with a mor
By Bob Fabian • October 23, 2026
Compare single-close construction loan lenders in Wisconsin beyond the rate. Learn what to ask about draws, rate locks, and experience. Get a quote.
Wisconsin residential building lot representing a single-close construction loan
By Bob Fabian • October 23, 2026
Own land in Wisconsin? Use your lot equity as a down payment on a single-close construction loan. One closing, one loan. See how lot and build financing works.
Wisconsin couple reviewing blueprints on building lot representing a single-close construction loan
By Bob Fabian • October 23, 2026
A single-close construction loan in Wisconsin combines build and permanent financing in one closing. Qualify once, save on costs, and convert automatically. Learn more.
Wood-frame house under construction with lumber, scaffolding, and workers on the roof
By Bob Fabian • October 8, 2026
Most people picture building a home as a spring project. Warm weather, fresh dirt, a foundation going in. They’re half right. Spring is when the building starts. But the buyers who break ground in spring didn’t start in spring. They started in the fall. Bob Fabian, a mortgage originator with Sistar Mortgage who speci
Wooden house framing under construction on a dirt lot, with ladders and tools in the sun.
By Bob Fabian • October 6, 2026
Most buyers rule out building a home before they ever run the numbers. They assume it costs too much, takes too long, and only makes sense for people with deep pockets. That assumption is getting old. The market has shifted, and Bob Fabian, a mortgage originator with Sistar Mortgage who specializes in construction fin