Build Your Dream Home with a Single Close Construction Loan in Hopewell, OH
When you’re ready to build your dream home in Hopewell, OH, the right financing makes all the difference. A single close construction loan is an ideal option for those who want a streamlined process, fewer closing costs, and confidence that their mortgage will be set from the start. With this type of loan, you combine construction financing and permanent mortgage financing into one simple package, saving you time, money, and stress.
Why Choose a Single Close Construction Loan?
Traditional construction financing often requires two separate closings: one for the construction loan and another for the permanent mortgage. With a single close loan, you only apply once, lock your interest rate upfront, and pay one set of closing costs. This program is designed to help you focus on your plan to build, rather than worrying about paperwork or adjusting to new requirements later.
Another benefit is the interest only payments during the construction phase. Instead of making full mortgage payments while your property is still being built, you only pay interest on what has been drawn from the loan. Once construction is complete, the loan automatically converts to a permanent mortgage, ensuring you don’t have to reapply.

Benefits of Single Close Construction Loans
Single close construction loans offer several advantages for Hopewell borrowers:
- One Time Closing: Pay closing costs once, unlike traditional construction loans, saving significant funds.
- Seamless Transition: The loan converts to a permanent mortgage after construction, streamlining the process.
- Cost Efficiency: A single close construction loan reduces lender fees and administrative costs, ideal for first-time homebuyers.
These benefits make the loan a smart choice for building your dream home in Hopewell’s welcoming community.
The Construction Phase in Hopewell
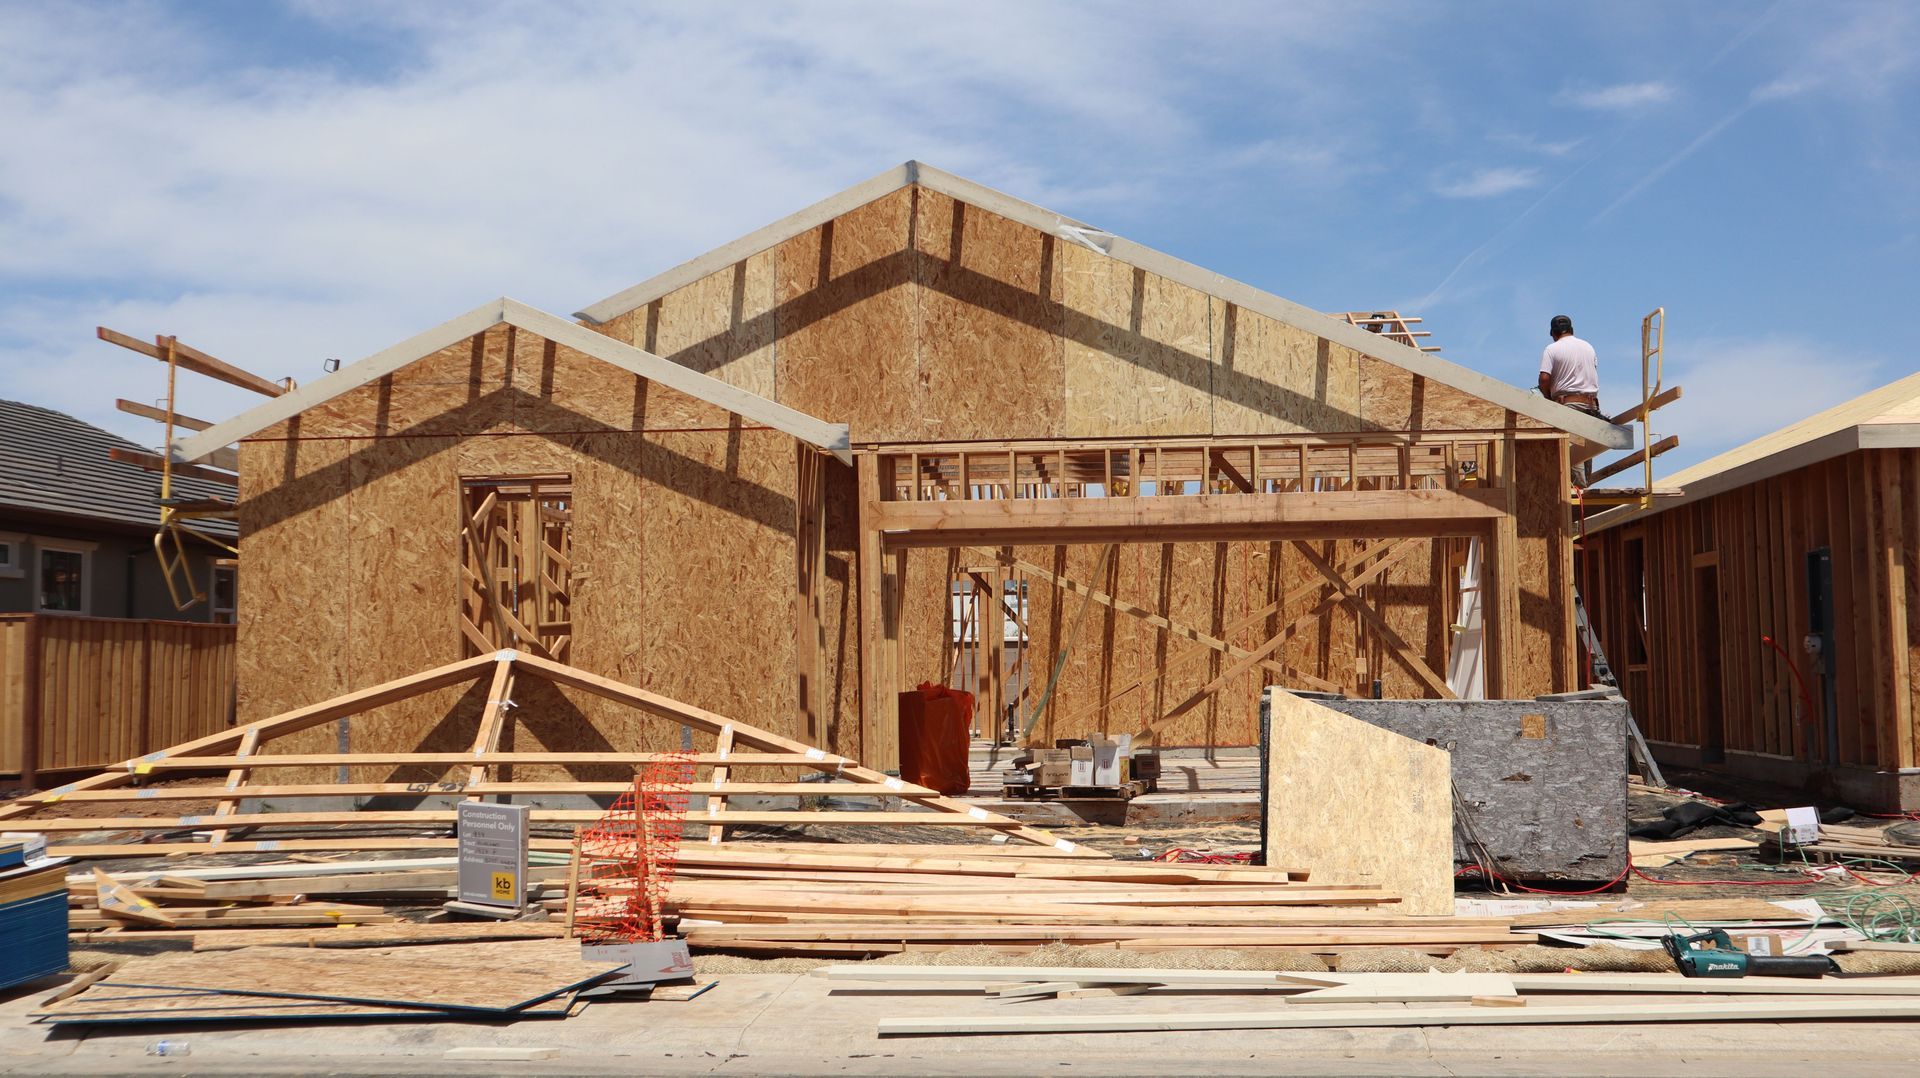
The construction phase typically lasts 6 to 12 months, with funds disbursed to the contractor to cover labor, materials, land purchase, and other costs. In Hopewell, where local regulations and the Muskingum River’s proximity may influence site preparation, a reputable builder ensures compliance with Muskingum County standards. An inspection and appraisal confirm the project’s quality before the loan converts to a permanent mortgage.
Down Payment Requirements
The down payment for a single close construction loan varies by loan program. Conventional loans typically require 5–20% of the total project cost, while Federal Housing Administration (FHA) loans may need as little as 3.5%. Veterans Affairs (VA) loans, ideal for eligible veterans in Hopewell, often require no down payment. Land already owned can be used as equity toward the down payment, reducing upfront costs for borrowers building in this affordable Ohio village.

Key Requirements to Qualify in Hopewell, OH
Lenders do have specific requirements for approval. The minimum credit score is one of the first factors to consider. While programs vary, a higher score can help you qualify for better interest rates and payment requirements. Debt-to-income ratio also plays a role, as lenders want to see that you can handle the payments once the home is complete.
In addition to your financial qualifications, you’ll need a solid plan for your construction project. This includes detailed information about the property, land purchase (if needed), and construction timeline. Having photos, architectural designs, and cost estimates ready at the time of application can make the approval process smoother.

What Costs Should You Expect?
Understanding the costs involved is key to making smart financial decisions. Closing costs will typically include appraisal fees, title charges, and lender fees. Because this is a single close program, you’ll only pay these costs once, rather than twice like in traditional construction financing.
Your interest rate will be locked in at the start, providing peace of mind in today’s changing mortgage market. This is especially valuable if you’re building over many months or years, since market rates could shift while your home is under construction. With one loan, you know exactly what to expect when the time comes to move in.
Steps to Get Started with Your Loan Application
If building in Hopewell is on your mind, the first step is to apply and get pre-approved. This ensures you know how much money you can borrow before making plans with your builder. During the application process, you’ll provide income documents, credit information, and details about your construction project.
Once approved, your loan will be set up with draw schedules so your builder can access funds as needed. You’ll make interest only payments during construction, keeping your monthly payments low until your home is ready. After completion, the loan will convert to your permanent mortgage, with no extra applications required.
Work with an Expert: Contact Bob Fabian today!
Choosing the right loan program is about more than numbers—it’s about ensuring your experience is smooth from start to finish. Whether you need information on how to qualify, details about payment requirements, or answers to questions about current loan programs, having a trusted contact makes all the difference.
Your dream home in Hopewell is within reach. Click to apply, get started today, and take the first step toward making your vision a reality.